
 80813-00200
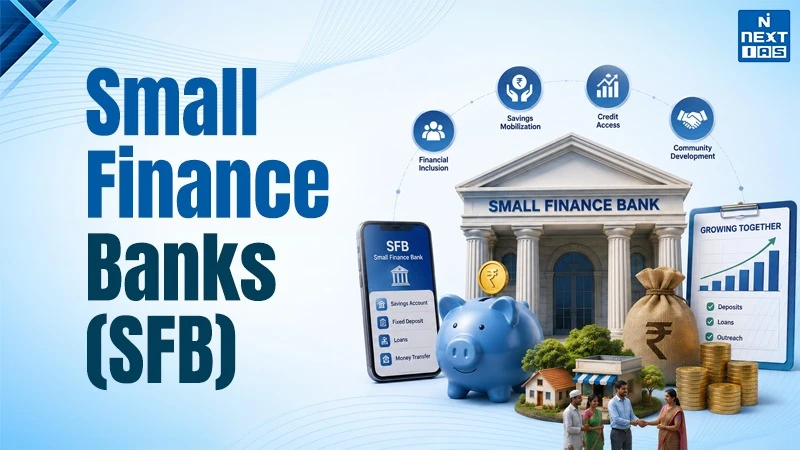
Small Finance Banks (SFBs) are specialised financial institutions which are set up in order to facilitate financial inclusion through provision of banking and credit services to the financially excluded segments of the population. The Small Finance Banks mainly cater to small enterprises, micro and small industries, farmers, poorer sections of society and employees of the unorganised sector.
Small Finance Banks may collect deposits and issue loans but they have to abide by the regulations issued by the Reserve Bank of India (RBI). The main characteristics of Small Finance Banks are priority sector lending, technology based banking, localized operations and increased access to financial services.
What are Small Finance Banks (SFB)?
- Small Finance Banks are financial institutions that offer services to unbanked and underserved regions of the country.
- They are registered as a public limited companies under the Companies Act, 2013.
- They can perform nearly all functions of a typical commercial bank, but on a much smaller scale.
- Small Finance Banks are a type of Differentiated Bank in India.
- Differentiated Banks under the Indian Banking System refer to those banks that cater to a specific segment of customers.
- The concept of Differentiated Banks was introduced in the Banking System in India by the RBI on the basis of the recommendations of the Nachiket Mor Committee in 2013 in order to offer specialized services or unique products designed specifically to suit a particular sector.
Objectives of SFB
- Access to financial services: The main objective of small finance banks is to increase access to financial services in rural areas as well as semi-urban areas.
- Basic banking services: They are envisaged to offer basic banking services to underserved sections of customers, including small and marginal farmers, small business units, micro and small industries, and even entities in the unorganised sector.
- Alternative institution: Small finance banks can provide an alternative to the existing institutions while maintaining their mandated focus on the informal sector, the informal sector, small and marginal farmers, small and medium businesses. This can help serve a variety of unserved clients in the hinterland and hence increase financial inclusion.
Features
- Can accept all types of deposits (CASA, FDRD etc.) like a commercial bank.
- They can give out depositor's money as loans to other customers, but in small areas of operation.
- It can also undertake non-risk-sharing financial activities. For example, the distribution of mutual fund units, pension products, insurance products, etc.
- They'll be opened under "Companies Act 2013".
- Target customers would be:
- small and marginal farmers;
- small business units;
- micro and small industries; and
- other unorganised sector entities.
- Focus would be on deposit and loans
Regulation of Small Finance Banks in India
- Small Finance Banks are registered as public limited companies under Companies Act 2013, and are licensed under section 22 of the Banking Regulation,1949.
- They are primarily governed by Banking Regulation Act, 1949 and RBI Act, 1934 and other relevant statutes.
Conditions Prescribed for Small Finance Banks
- 25% branches in rural area.
- They must give 50% of their loans to MSME sector.
- Minimum networth shall be ₹100 crore from the date of commencement and has to be increased to minimum ₹200 crore in five years.
- Small Finance Banks are required to maintain a minimum capital adequacy ratio of 15 percent of its risk-weighted assets (RWA) on a continuous basis.
Differences Between Small Finance Banks and Payment Banks
Small Finance Banks and Payment Banks, both, are types of differentiated banks in India. However, they differ from each other in terms of their very objective and conception as described below.
| Criteria | Small Finance Banks | Payment Banks |
|---|---|---|
| Registration and Licensing | Registered under Companies Act Licensed under Banking Regulation Act, 1949 | Registered under Companies Act, 2013 Licensed under Banking Regulation Act, 1949 |
| Eligibility | Resident Indians, Private Companies, Societies, NBFCs, MFIs, Local Area Banks | Pre-paid Payment Instrument (PPI) Providers, Resident individuals; NBFCs; Telecom Companies, super-market chains, public sector entities etc. |
| Minimum Capital Requirements | ₹100 crores. (To be increased to ₹200 crores within 5 years) | ₹100 crores |
| FDI Allowed | Yes. Up to 74% | Yes. Up to 74% |
| Accept Deposits | Yes | Only Demand Deposits. No Fixed Deposits and NRI Deposits |
| Restrictions on Deposits | No Restrictions | Up to ₹1 Lakhs |
| Deposit Insurance Available? | Yes | Yes |
| Can Lend Loans | Yes. At least 50 per cent of its loan portfolio must consist of loans and advances of up to ₹25 lakh. | No |
| Issue Debit/Credit Card | Both can be issued | Only Debit Card. No Credit Card |
| Set up based upon recommendations of | Nachiket Mor Committee | Nachiket Mor Committee |
| Committee to Evaluate Applications for License | Usha Thorat Committee | Nachiket Mor Committee |
| Statutory Liquidity Ratio (SLR) and Cash Reserve Ratio (CRR) Applicable | CRR and SLR Applicable | CRR Applicable; SLR: 75% of Net Demand and Time Liabilities (NDTL) |
| BASEL Norms Applicable | Yes. 15% of Risk Weighted Assets (RWAs) | Yes. 15% of Risk Weighted Assets (RWAs) |
| Priority Sector Lending (PSL) Norms Applicable | Yes. Target: 75%. | No. Can't lend Loans |
| Examples | Ujjlvan, Utkarsh, Jana, Au etc. | Airtel, India Posts Payment Bank, Paytm, FINO etc. |
FAQs of SFB
What are the Small Finance Banks (SFBs)?
The Small Finance Banks are specialized banks providing savings, credit, and other financial facilities to underprivileged and poor segments of society.
Why were Small Finance Banks founded?
Small Finance Banks were founded for the sake of ensuring financial inclusion by increasing the availability of formal banking and low-cost credit.
Who are the primary beneficiaries of SFBs?
Agriculture, small enterprises, microenterprises, poor families, and workers in the informal economy are some major beneficiaries.
Which institution oversees the operations of SFBs in India?
The Reserve Bank of India (RBI) oversees the activities of the SFBs.
How do SFBs contribute to financial inclusion?
The SFBs help in expanding banking reach, savings collection, and credit delivery to the unserved areas.
