
 80813-00200
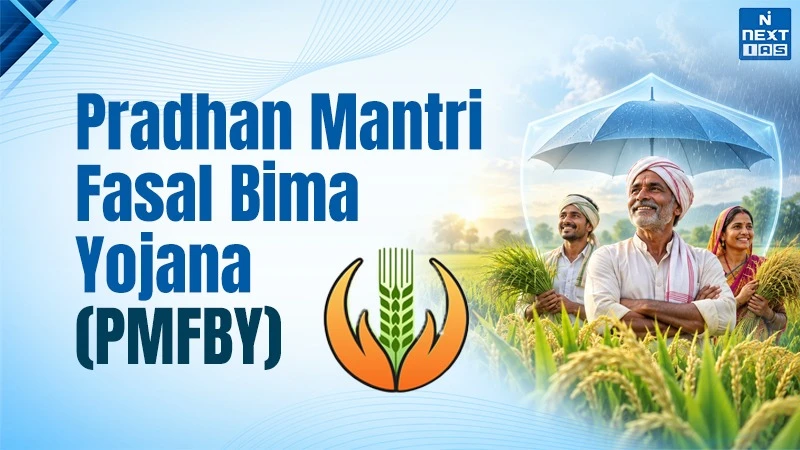
Pradhan Mantri Fasal Bima Yojana (PMFBY) is an initiative introduced in the year 2016 Kharif season for safeguarding the farmers from non-preventable natural risks and crop losses. PMFBY covers non-preventable natural risks including drought, floods, storms, hailstorms, pest attacks, plant disease, as well as some post-harvest risks.
Farmers contribute a premium at a limited rate of 2% on kharif crops, 1.5% on rabi crops, and 5% on annual commercial and horticultural crops, whereas the rest of the premium amount is provided by the government. It has also started utilising the digital media, satellite imagery, mobile technology, and other technologically advanced systems in order to ensure more transparency and claim settlement in the process.
About the Pradhan Mantri Fasal Bima Yojana (PMFBY)
- The PMFBY, or Pradhan Mantri Fasal Bima Yojana ( PMFBY) is a government subsidized crop insurance program that was launched in 2016 and is designed to safeguard farmers against financially harmful economic losses due to natural disasters, infestations and disease.
- The objectives of the PMFBY program are to secure a more dependable agricultural income, to improve the technological advancement of agriculture, and to promote improved financial inclusion and access along the agricultural supply chain.
- As part of the PMFBY program, farmers are only required to pay a minimal premium -- 2% for Kharif seasonal crops, 1.5% for Rabi seasonal crops, and 5% for commercial or horticultural crops, with the government subsidizing the remainder of the premium for the farmer.
- Claims payouts under the PMFBY program occur based on crop losses estimated using high-tech modalities, including drone imaging, smart sampling and satellite imaging technology.
- The PMFBY program is compulsory for farmers with some form of institutionalized loan, and otherwise voluntary for all other farmers.
- The PMFBY program underwent an overhaul in 2020 to promote more transparency, to increase voluntary participation and to expedite settlements of claims.
Key Features
- Low Premium Rates for Farmers:
- 2% for Kharif crops
- 1.5% for Rabi crops
- 5% for commercial and horticultural crops
- The differential between the total premium and farmer premium is subsidized by a combination of the central and state government.
- Comprehensive Risk Coverage: There is coverage for calamities that result in pre-sowing to post-harvest loss of yield, which includes losses caused by drought, flood, and cyclone, loss caused by pests and diseases and localized calamities such as landslides, hailstorms, and inundation.
- Use of Advanced Technology: Remote sensing, drones, and satellite imagery are used to aid in assessing crop damage and smart sampling methods are used to estimate the total final yield in an accurate and transparent fashion.
- Widespread Coverage: This coverage is applicable for all food crops and oilseeds as well as the commercial/horticultural crops located in the state.It also includes tenant and sharecropper farmers.
- Compulsory and Voluntary Enrollment: Enrollment in this scheme is compulsory for farmers who take out an institutional loan.This scheme is voluntary for non-loanee farmers.
Objectives of the PMFBY
- Initiated in 2016, the Pradhan Mantri Fasal Bima Yojana (PMFBY) is intended to support the agriculture sector by safeguarding farmers from financial loss and exposure to risks arising from natural disasters, pests, and diseases.
- The scheme is paramount for providing income stability, reducing risk, and ensuring sustainability in agriculture.
Key Aims of the PMFBY Scheme:
- Financial Support to Farmers': Provide farmers protection against agricultural losses on account of droughts, floods, cyclones, hail storms, pests, and diseases.Reduce financial stress and indebtedness because of unpredictable weather and crop failures.
- Affordable and Inclusive Crop Insurance Plans: Provide better access through making premium rates low (2% for Kharif, 1.5% for Rabi, & 5% for commercial/ horticultural crops). Improve access, affordability, and participation of all farmers, especially smaller farmers and farmers with marginal farm size.
- Encourage Technology Adoption in Agriculture: To promote modern farming techniques and scientific farming practices using risk management strategies could ease reliance on informal credit or distress sale of farmers' production.
- Ensure Quick and Transparent Claims Settlement: Assess crop losses using technology like drones, satellites, and remote sensing while using accurate historical data and timely reporting.Support fast and timely claims payments, within 30 days from the claim date.
- Encourage Sustainable Agriculture and Rural Development: Improve agricultural resilience from climate impacts. Strengthening rural economies through ensuring farmer's livelihoods and increasing food security.
- In 2020, PMFBY was updated and improved by making it voluntary, increasing transparency and delivery.
Significance
- The Pradhan Mantri Fasal Bima Yojana (PMFBY), initiated in 2016, is a vital measure to assure protection for farmers' livelihoods through financial assistance to recover from crop loss due to natural catastrophes, plants, pests, and diseases.
- PMFBY contributes to agricultural risk management, rural development, and national food security.
- Key importance: Financial Assurance and Risk Mitigation PMFBY helps farmers recover for crop loss due to severe weather, including droughts, floods, cyclones, hail and landslides.
- Thus avoiding the financial burden when losing income due to uncertain loss occurrences.
- Encouraging Agricultural Investments Assured insurance allows farmers to adopt modern farming practices and await higher yield varieties and continue sustainable agricultural practices.
- Reduce dependency on informal credit sources and distress selling of produce. Affordable and Inclusive Coverage Affordable for small and marginal farmers because of low premium rates of 2 % for kharif, 1.5% for rabbi and 5% for commercial or horticultural crop loss insurance. Very much include tenant and sharecropping farmers.
- Utilization of Modern Technology: Employs satellite imagery, drone technology and remote sensing for evidence of crop loss, assessment and timely settlement for claims.
- Digital technologies used reduce transaction costs and facilitate transparency and accountability of files and payment services to qualified claimants.
- Further Rural Economy and Food Security Safbands farmers' income from crop loss, as an integral part of the stability of agriculture.
Lacunae of the Pradhan Mantri Fasal Bima Yojana
The Pradhan Mantri Fasal Bima Yojana (PMFBY) seeks to assure farmers of financial cover, but various limitations on the scheme restrict its role in delivering holistic crop insurance. The limitations can be grouped as follows:
- Delayed Claim Settlement: Farmers frequently wait long amounts of time before receiving claim payments that can severely impact their finances; insurance companies cite late claim settlements as a result of delayed fund disbursement from states.
- Low Farmer Awareness and Participation: Due to low farmer education and low trust in the insurance sector among small and marginal farmers, there is a lack of knowledge about the enrollment process and how to file an insurance claim. Farmers are aware of payments in premiums being deducted from their borrowing accounts, but they find it difficult to trust the whole system because of the lack of transparency.
- High Cost of Premium for the Government: Although farmers are able to pay low premiums, the costs of covering potential claims puts a high financial burden on the government. As a result some states do not allocate funds for future premiums because they find it difficult to pay the subsidy regularly.
- Limited Coverage, Exclusions and Duration: As previously mentioned, crop loss done as a result of claims assessment do not insure losses due to wild animals, labor shortages, or price changes, nor have a payout that lasts long covered post harvest.
- Private Insurance Company: PMFBY is primarily a profit for private insurance companies, who often do not invest enough effort to provide welfare for farmers. Under conditions of not having any viable competition or transparency, there are times when a claim is rejected despite being a valid claim.
Key Pointers on PMFBY for UPSC CSE Prelims
- Launch Year: 2016
- Ministry: Ministry of Agriculture & Farmers Welfare
- Objective: To provide financial protection to farmers against losses caused by either crop failure due to natural calamities or pest and disease infestation.
- Premium Rates:
- 2% for Kharif crops
- 1.5% for Rabi crops
- 5% for commercial and horticultural crops
- The remaining premium will be shared by both central and state governments.
- Risk Coverage:
- It covers pre-sowing to post-harvest losses due to droughts, floods, cyclones, pests, diseases, hailstorms, and landslides.
- Includes localized calamities like water logging and storm damage.
- Beneficiaries:
- All farmers (along with tenant and sharecroppers) cultivating notified crops under the notified areas.
- Compulsory for loanee farmers and option for non-loanee farmers.
- Technology Use:
- Remote sensing, drones, and satellite imagery for a transparent crop loss assessment.
- Processing of claims is digitized for fast disbursement.
- 2020 Reforms:
- It has been made voluntary for all farmers.
- Flexible implementation of the scheme is given to the states.
- Insurance companies have the obligation to settle claims within a period of 30 days.
- Challenges:
- Delayed settlements of claims on account of delays in fund availability from the state government.
- Low awareness among farmers and most private insurers focusing on profits.
- Withdrawal of some states due to heavy subsidy burden.
- Significance:
- Ensures not only income stability for farmers but also lessens agricultural distress.
- Promotes modern agricultural practices and financial inclusion.
FAQs
When was PMFBY launched?
The Pradhan Mantri Fasal Bima Yojana was launched in 2016 with an aim of offering affordable crop insurance to farmers.
What is the premium paid by the farmers under PMFBY?
Farmers pay 2% premium on Kharif crop, 1.5% premium on Rabi crops and 5% premium on annual commercial and horticultural crops.
What kind of risks are covered under PMFBY?
PMFBY covers the risks of drought, floods, cyclones, hailstorm, pests, diseases, etc.
4. What is the advantage of PMFBY for the farmers?
PMFBY assists in compensating crop losses and helps stabilizing the farmers' income.
